Every industry has its own nuances. We take that into consideration and approach business solutions with the specific lens required of your field. Our teams are comprised of talent with relevant experience and we’re prepared to meet every challenge.
CMS Rural Health Transformation Program: Missed Year 1 funding? How to prepare for Year 2 opportunities
Lorem ipsum dolor set
FSG Quarterly Financial Services Update - Q3 2026
Lorem ipsum dolor set
Replay: Financial Services Group Quarterly Accounting and Reporting Update
Lorem ipsum dolor set
Workforce Development: Addressing physician burnout through a holistic operating model
Lorem ipsum dolor set
What ESOP sellers need to know about Section 1042 rollovers
Lorem ipsum dolor set
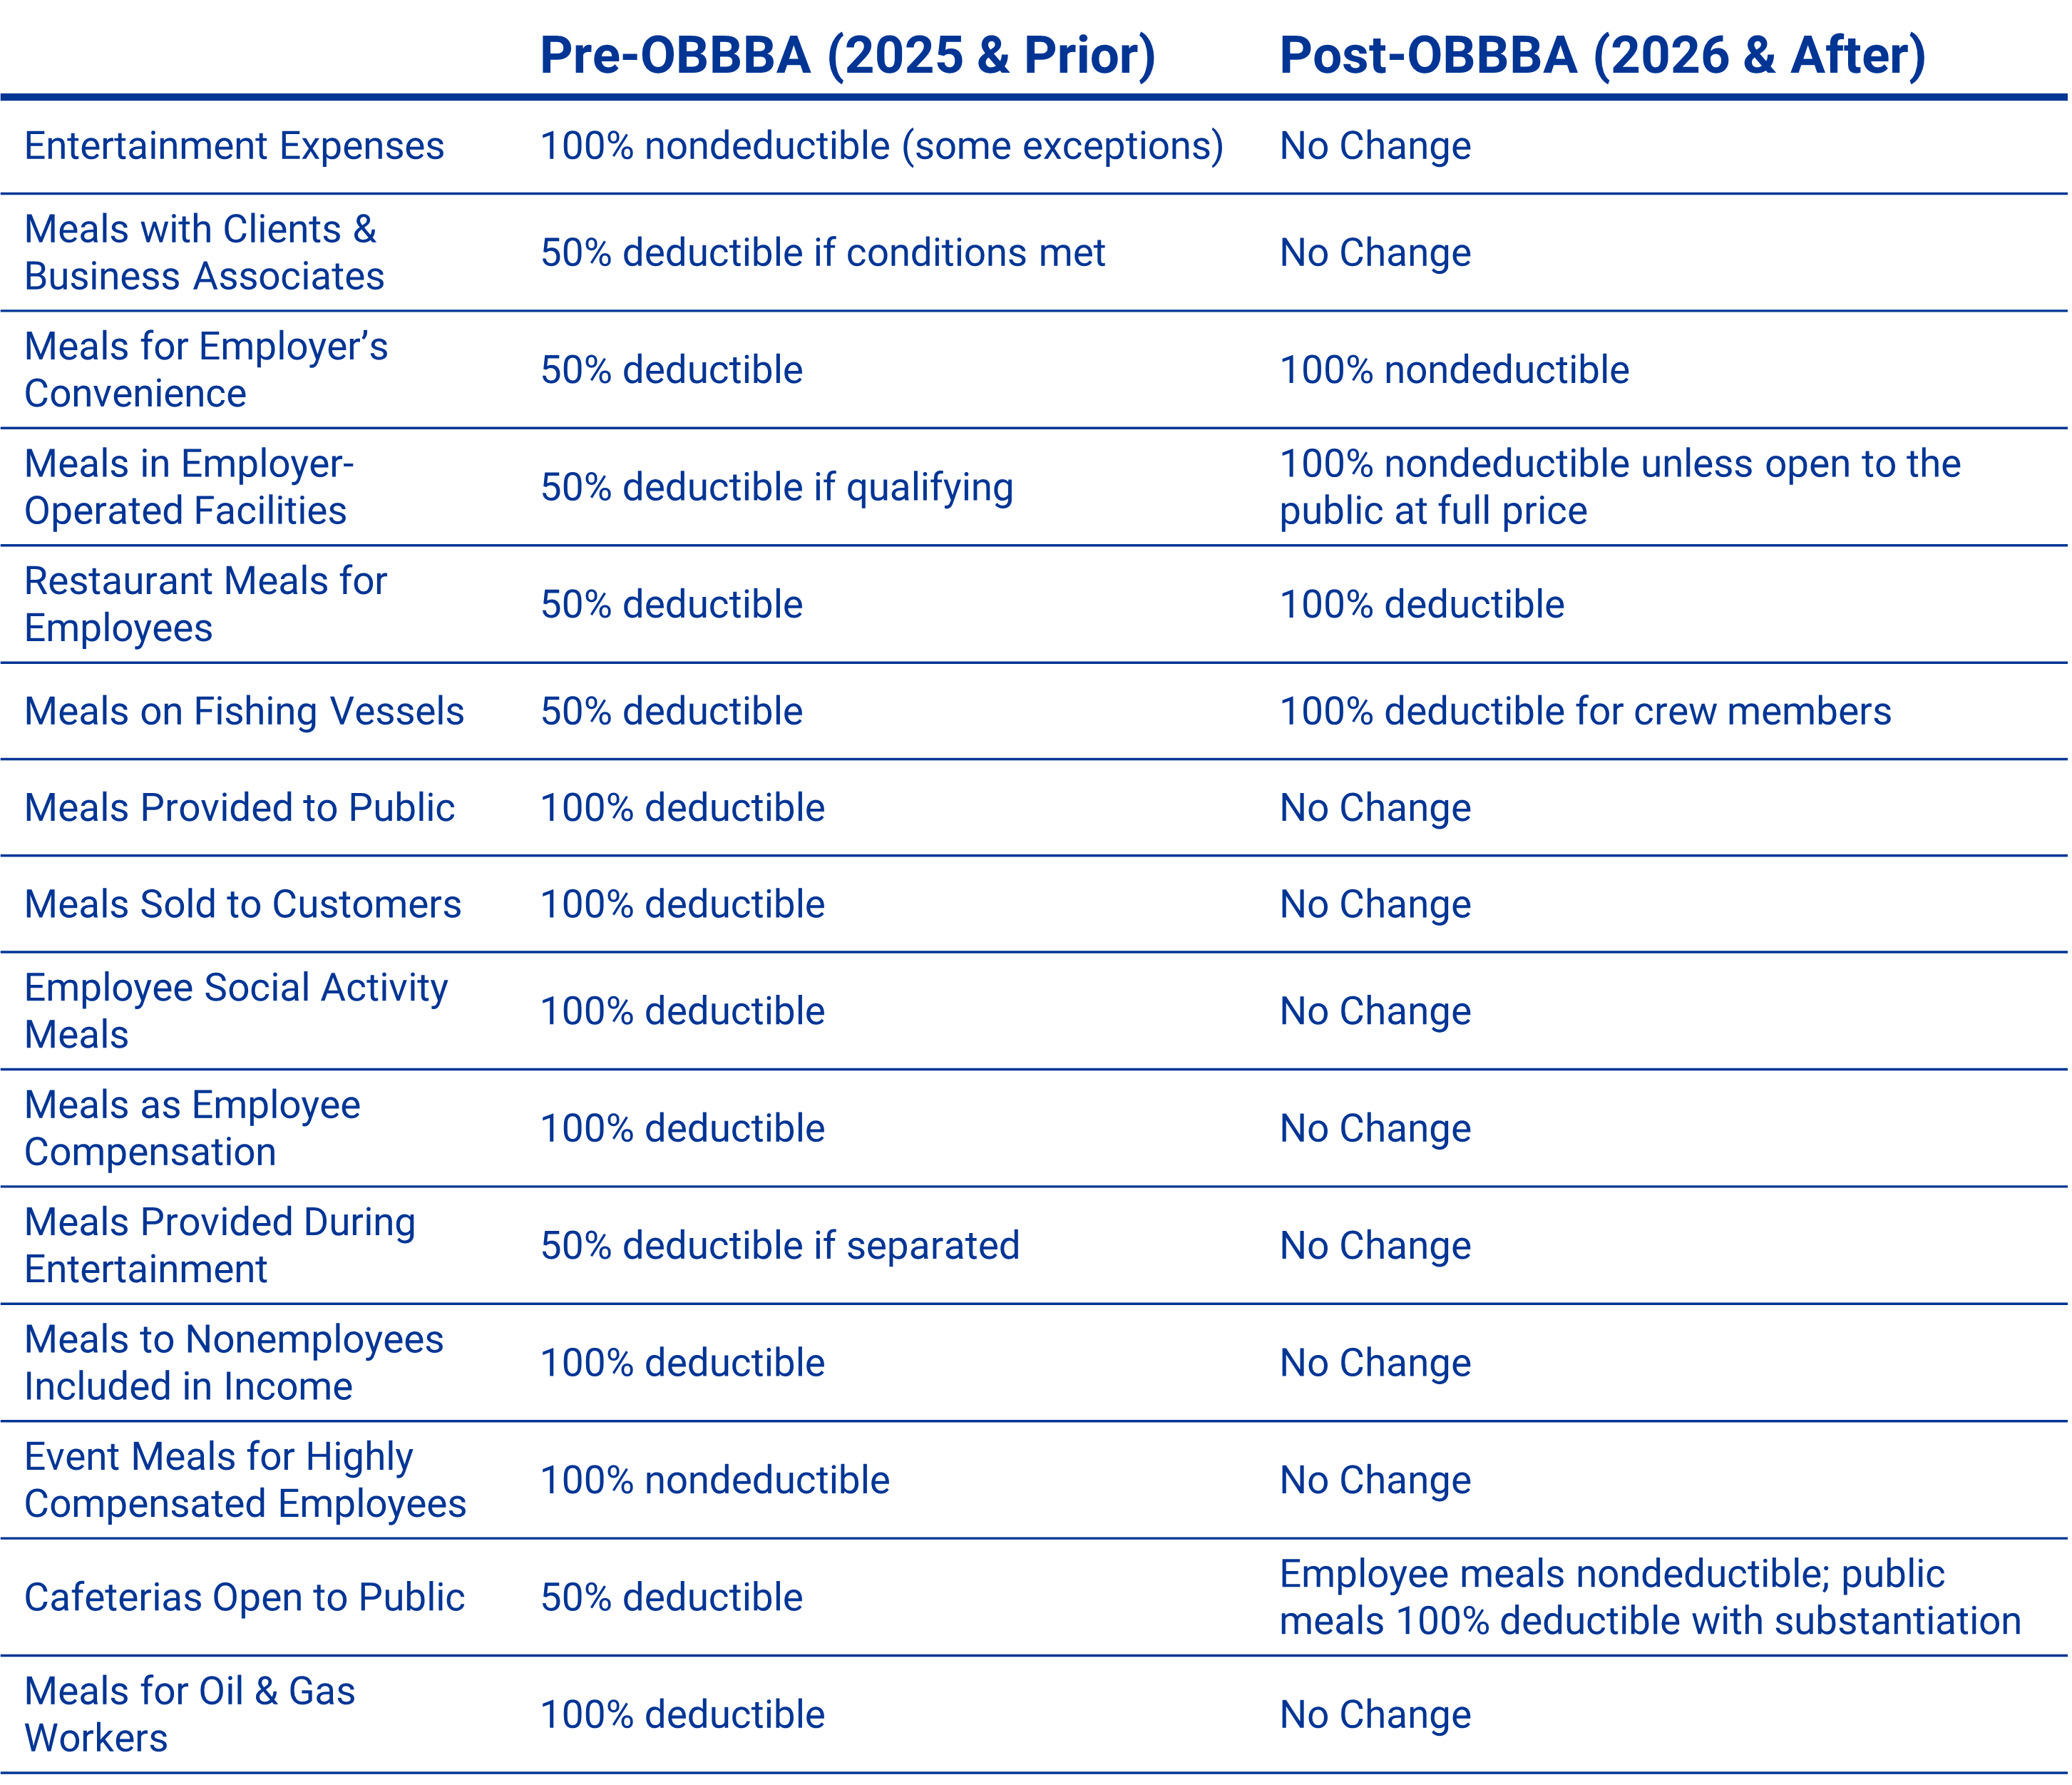
The One Big Beautiful Bill Act (OBBBA) brings new rules for meals and entertainment deductions beginning in tax years after December 31, 2025. While the categories haven’t changed much, the deductibility rules have. For business owners, this means far fewer employer provided meals will qualify. Only a limited set of specific situations will still allow a deduction under the new law.
At a Glance
Entertainment costs stay nondeductible (with only a few narrow exceptions).
Business meals remain 50% deductible, but you still need proper documentation and a clear business purpose.
Employer-provided meals become mostly nondeductible, including snacks, coffee, overtime meals, and meals served in on-site cafeterias. Exceptions include:
Meals provided by restaurants to their employees
Meals on fishing vessels
Meals sold to the public at full price in employer-operated cafeterias
Below is a table summarizing the changes:
Action Steps for Employers
Since the OBBBA significantly limits the deductibility of employer-provided meals, most businesses will need to make some operational and accounting adjustments. As you prepare for the 2026 tax year, consider the following:
Review how your company currently provides meals and snacks. Identify where food is being offered (e.g., break rooms, cafeterias, meetings, overtime support) and determine which items will no longer be deductible.
Update internal policies and communication. Employees may need clarity on what qualifies as a business meal going forward. Simple updates to handbooks, expense policies, or manager guidance can prevent confusion.
Adjust your accounting and tax processes. You may need new general ledger categories, revised tracking procedures, and updated tax provision and return calculations to reflect the new limitations.
Evaluate operational and financial impact. For companies with cafeterias or regular meal offerings, it may be worth assessing costs, pricing, and whether changes to operations make sense under the new rules.
We Can Help
The Elliott Davis team helps business owners adapt to the new tax requirements and the strategic decisions that follow. We can assist with policy updates, recordkeeping, and planning so you’re well prepared for the 2026 tax year. Contact us to discuss how these changes may affect your business and what steps to take next.
The information provided in this communication is of a general nature and should not be considered professional advice. You should not act upon the information provided without obtaining specific professional advice. The information above is subject to change.
How a construction contractor restored profitability after growth exposed financial blind spots
A growing construction contractor moved to accrual accounting and integrated job-cost tools, gaining real-time margin visibility and smoother close.
Case Study
August 4, 2026
Data governance and third-party oversight: Key risk areas for specialty finance companies
Learn how specialty finance companies can strengthen data governance, oversee third-party servicers, reduce audit risk, and improve financial reporting.
Article
July 30, 2026
What a recent high-profile cybersecurity incident reveals about healthcare cyber risk
A recent cyberattack serves as a reminder to the healthcare community to stay vigilant against cybercrime.
Article
July 29, 2026
Managing state tax exposure for growing businesses: When to consider a voluntary disclosure agreement (VDA)
Learn when a VDA may help reduce penalties, resolve historical tax liabilities, and strengthen multi-state tax compliance.
Article
July 28, 2026
Trends in charitable giving: Tax advantages of partnership interest donations
Learn the tax advantages, risks, valuation rules, and estate planning benefits of charitable partnership interest donations.
Article
July 17, 2026
CMMC phase II requirements suspended: Next steps for defense contractors
The DoD has suspended CMMC Phase II requirements. Learn what the pause means, ongoing compliance obligations, and key next steps for defense contractors.