
DO NOT PUBLISH


Table of Contents
Share with network
Related Insights
The One Big Beautiful Bill Act (OBBBA) brings new rules for meals and entertainment deductions beginning in tax years after December 31, 2025. While the categories haven’t changed much, the deductibility rules have. For business owners, this means far fewer employer provided meals will qualify. Only a limited set of specific situations will still allow a deduction under the new law.
Below is a table summarizing the changes:
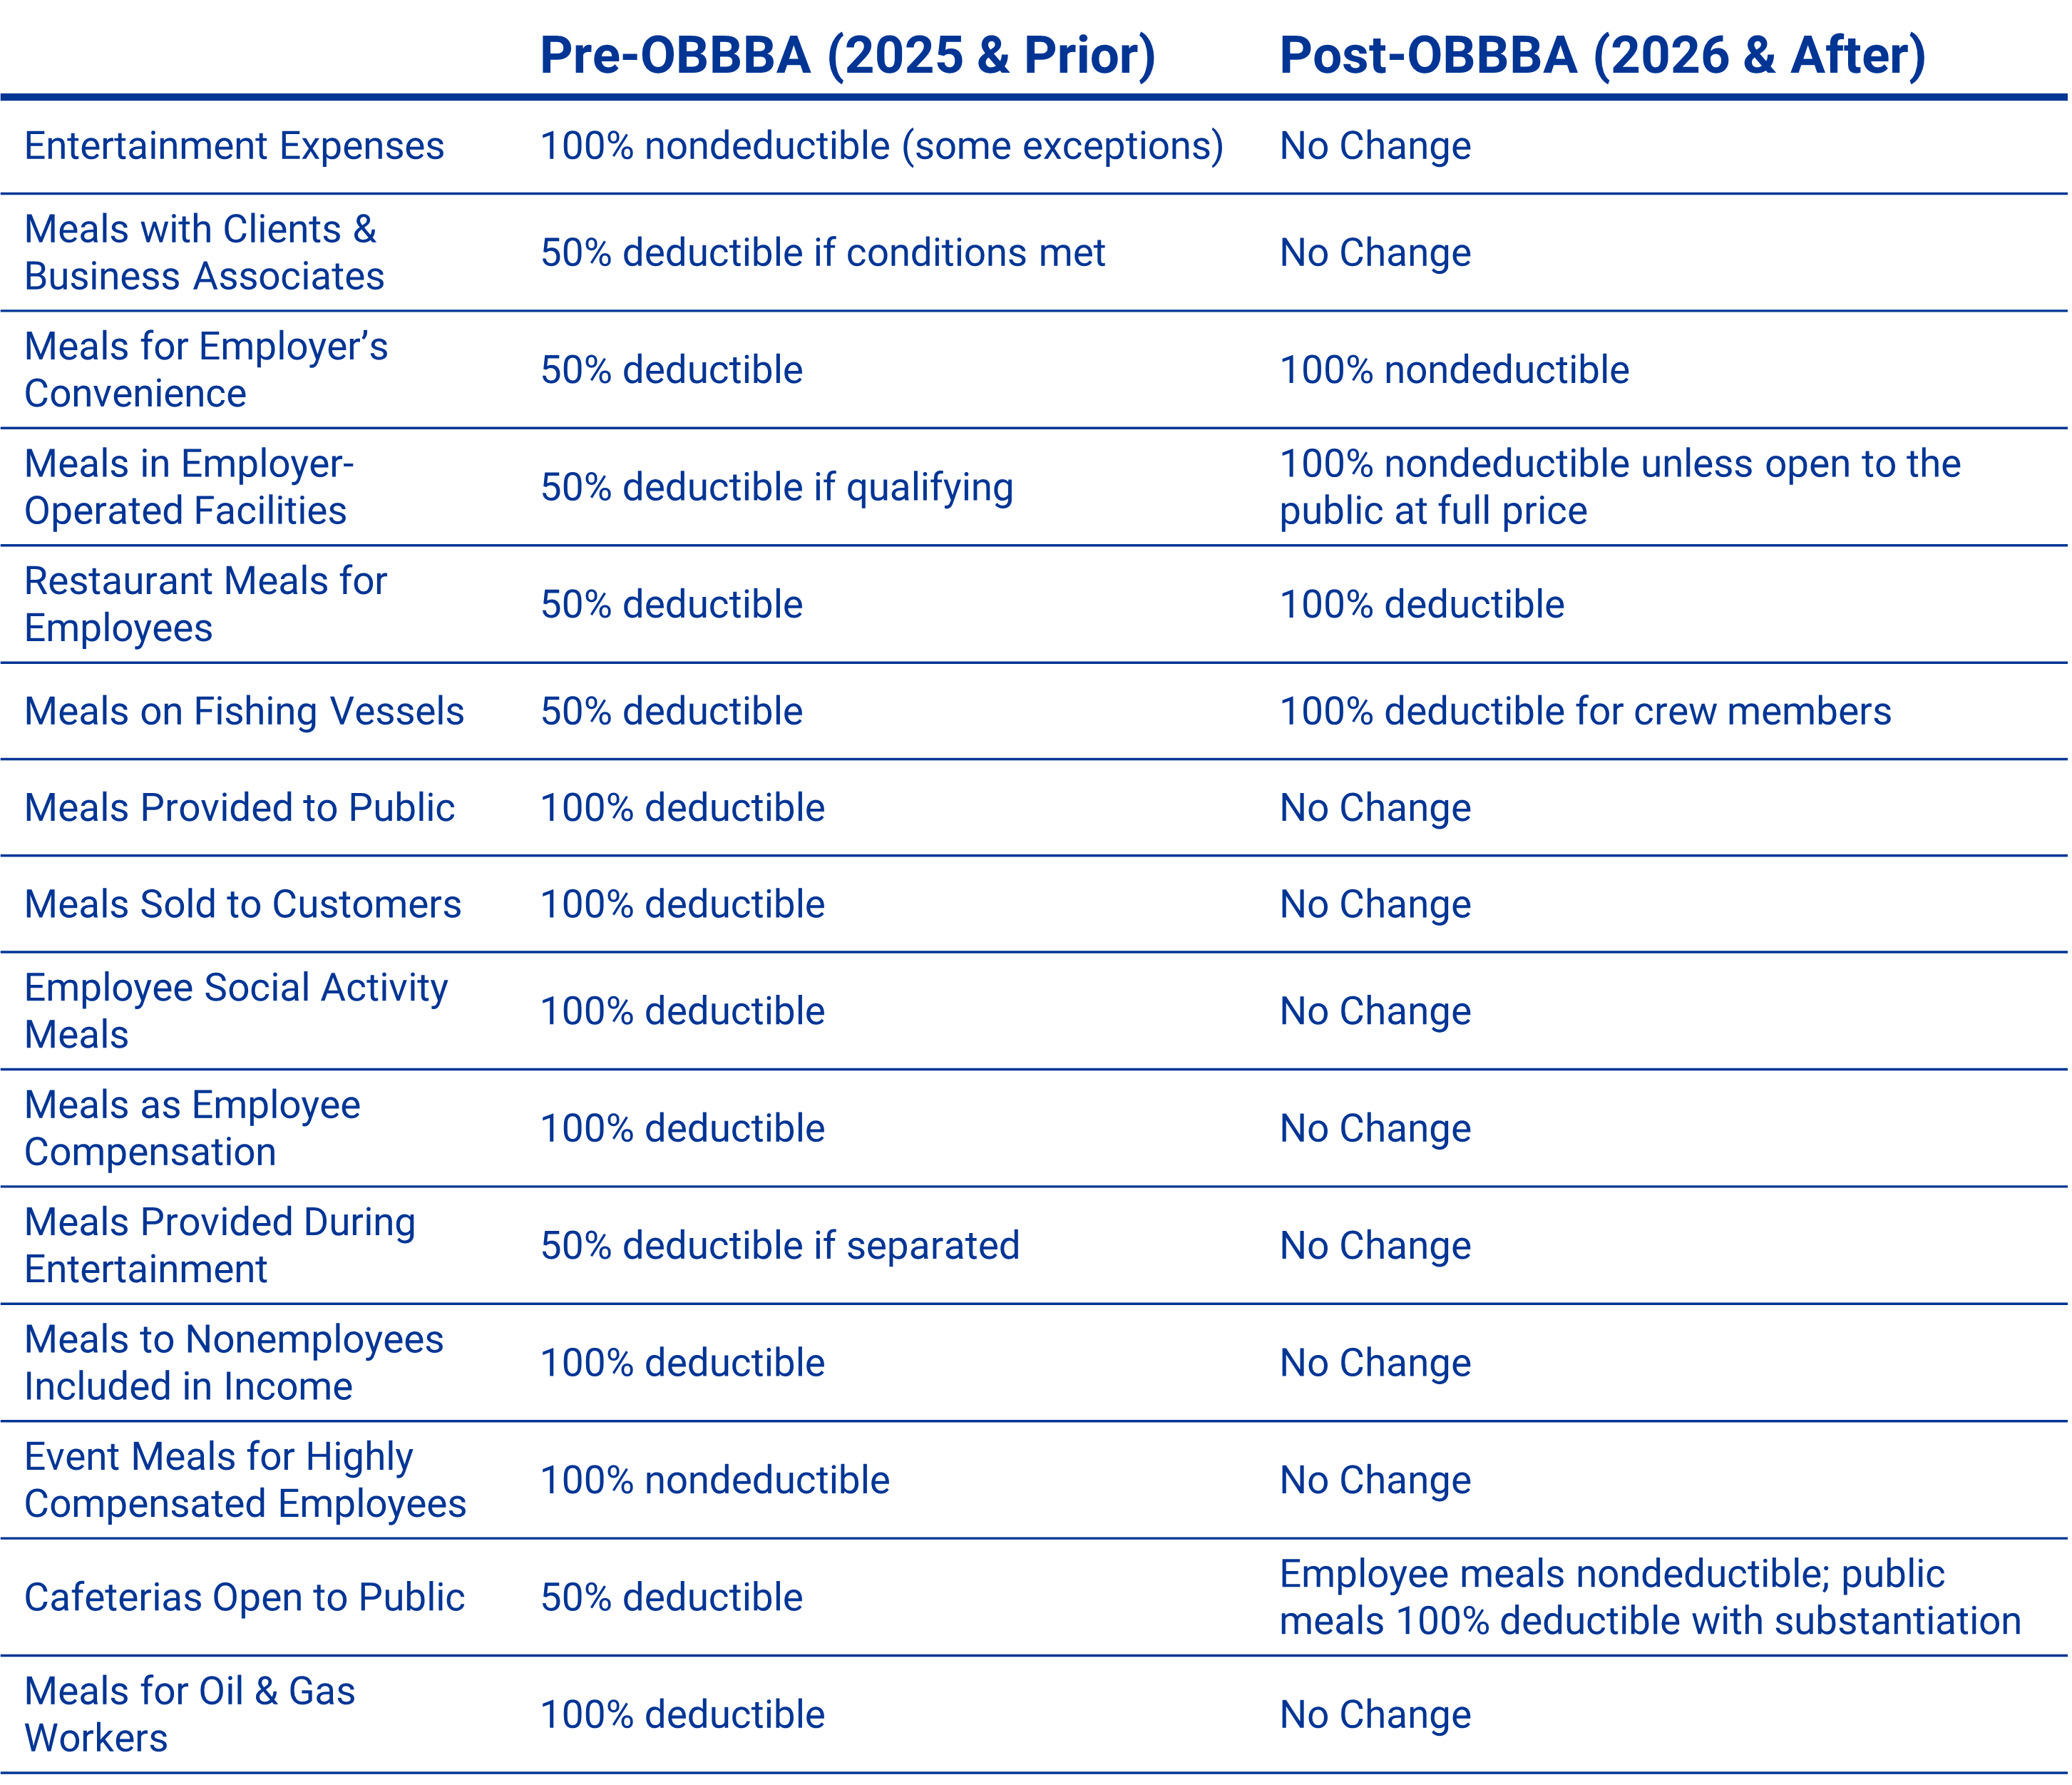
Since the OBBBA significantly limits the deductibility of employer-provided meals, most businesses will need to make some operational and accounting adjustments. As you prepare for the 2026 tax year, consider the following:
The Elliott Davis team helps business owners adapt to the new tax requirements and the strategic decisions that follow. We can assist with policy updates, recordkeeping, and planning so you’re well prepared for the 2026 tax year. Contact us to discuss how these changes may affect your business and what steps to take next.
The information provided in this communication is of a general nature and should not be considered professional advice. You should not act upon the information provided without obtaining specific professional advice. The information above is subject to change.
the
authors
related
insights

Audit ready: A first-time guide for private equity fund managers — SBIC vs. regular structures
Discover how private equity fund managers can prepare for audits at the fund level. Learn key differences between SBIC and non-SBIC structures, common pitfalls, and six practical steps to ensure compliance and protect investor confidence.
FASB Alert: ASU 2025-08 brings major CECL reform for purchased loan accounting
The FASB introduced significant changes to the CECL standard, addressing purchased financial asset accounting and acquisition reporting. The new guidance applies to fiscal years beginning after December 15, 2026, with early adoption permitted.
Are you ready to protect your investment with rigorous compliance?
Discover how real estate firms, REITs, and QOFs stay compliant through specialized requirements and periodic testing. Learn operational best practices when managing fixed assets, planning for estimated tax payments, and preparing for audit.
Top 5 overlooked tax-saving opportunities when operating multiple businesses
Discover tax-saving opportunities for business owners managing multiple entities. Learn how entity structure, strategic elections, advanced planning tools, and knowledgeable advisors can help you reduce tax liability and maximize after-tax income.