Every industry has its own nuances. We take that into consideration and approach business solutions with the specific lens required of your field. Our teams are comprised of talent with relevant experience and we’re prepared to meet every challenge.
CMS Rural Health Transformation Program: Missed Year 1 funding? How to prepare for Year 2 opportunities
Lorem ipsum dolor set
FSG Quarterly Financial Services Update - Q3 2026
Lorem ipsum dolor set
Replay: Financial Services Group Quarterly Accounting and Reporting Update
Lorem ipsum dolor set
Workforce Development: Addressing physician burnout through a holistic operating model
Lorem ipsum dolor set
What ESOP sellers need to know about Section 1042 rollovers
Lorem ipsum dolor set
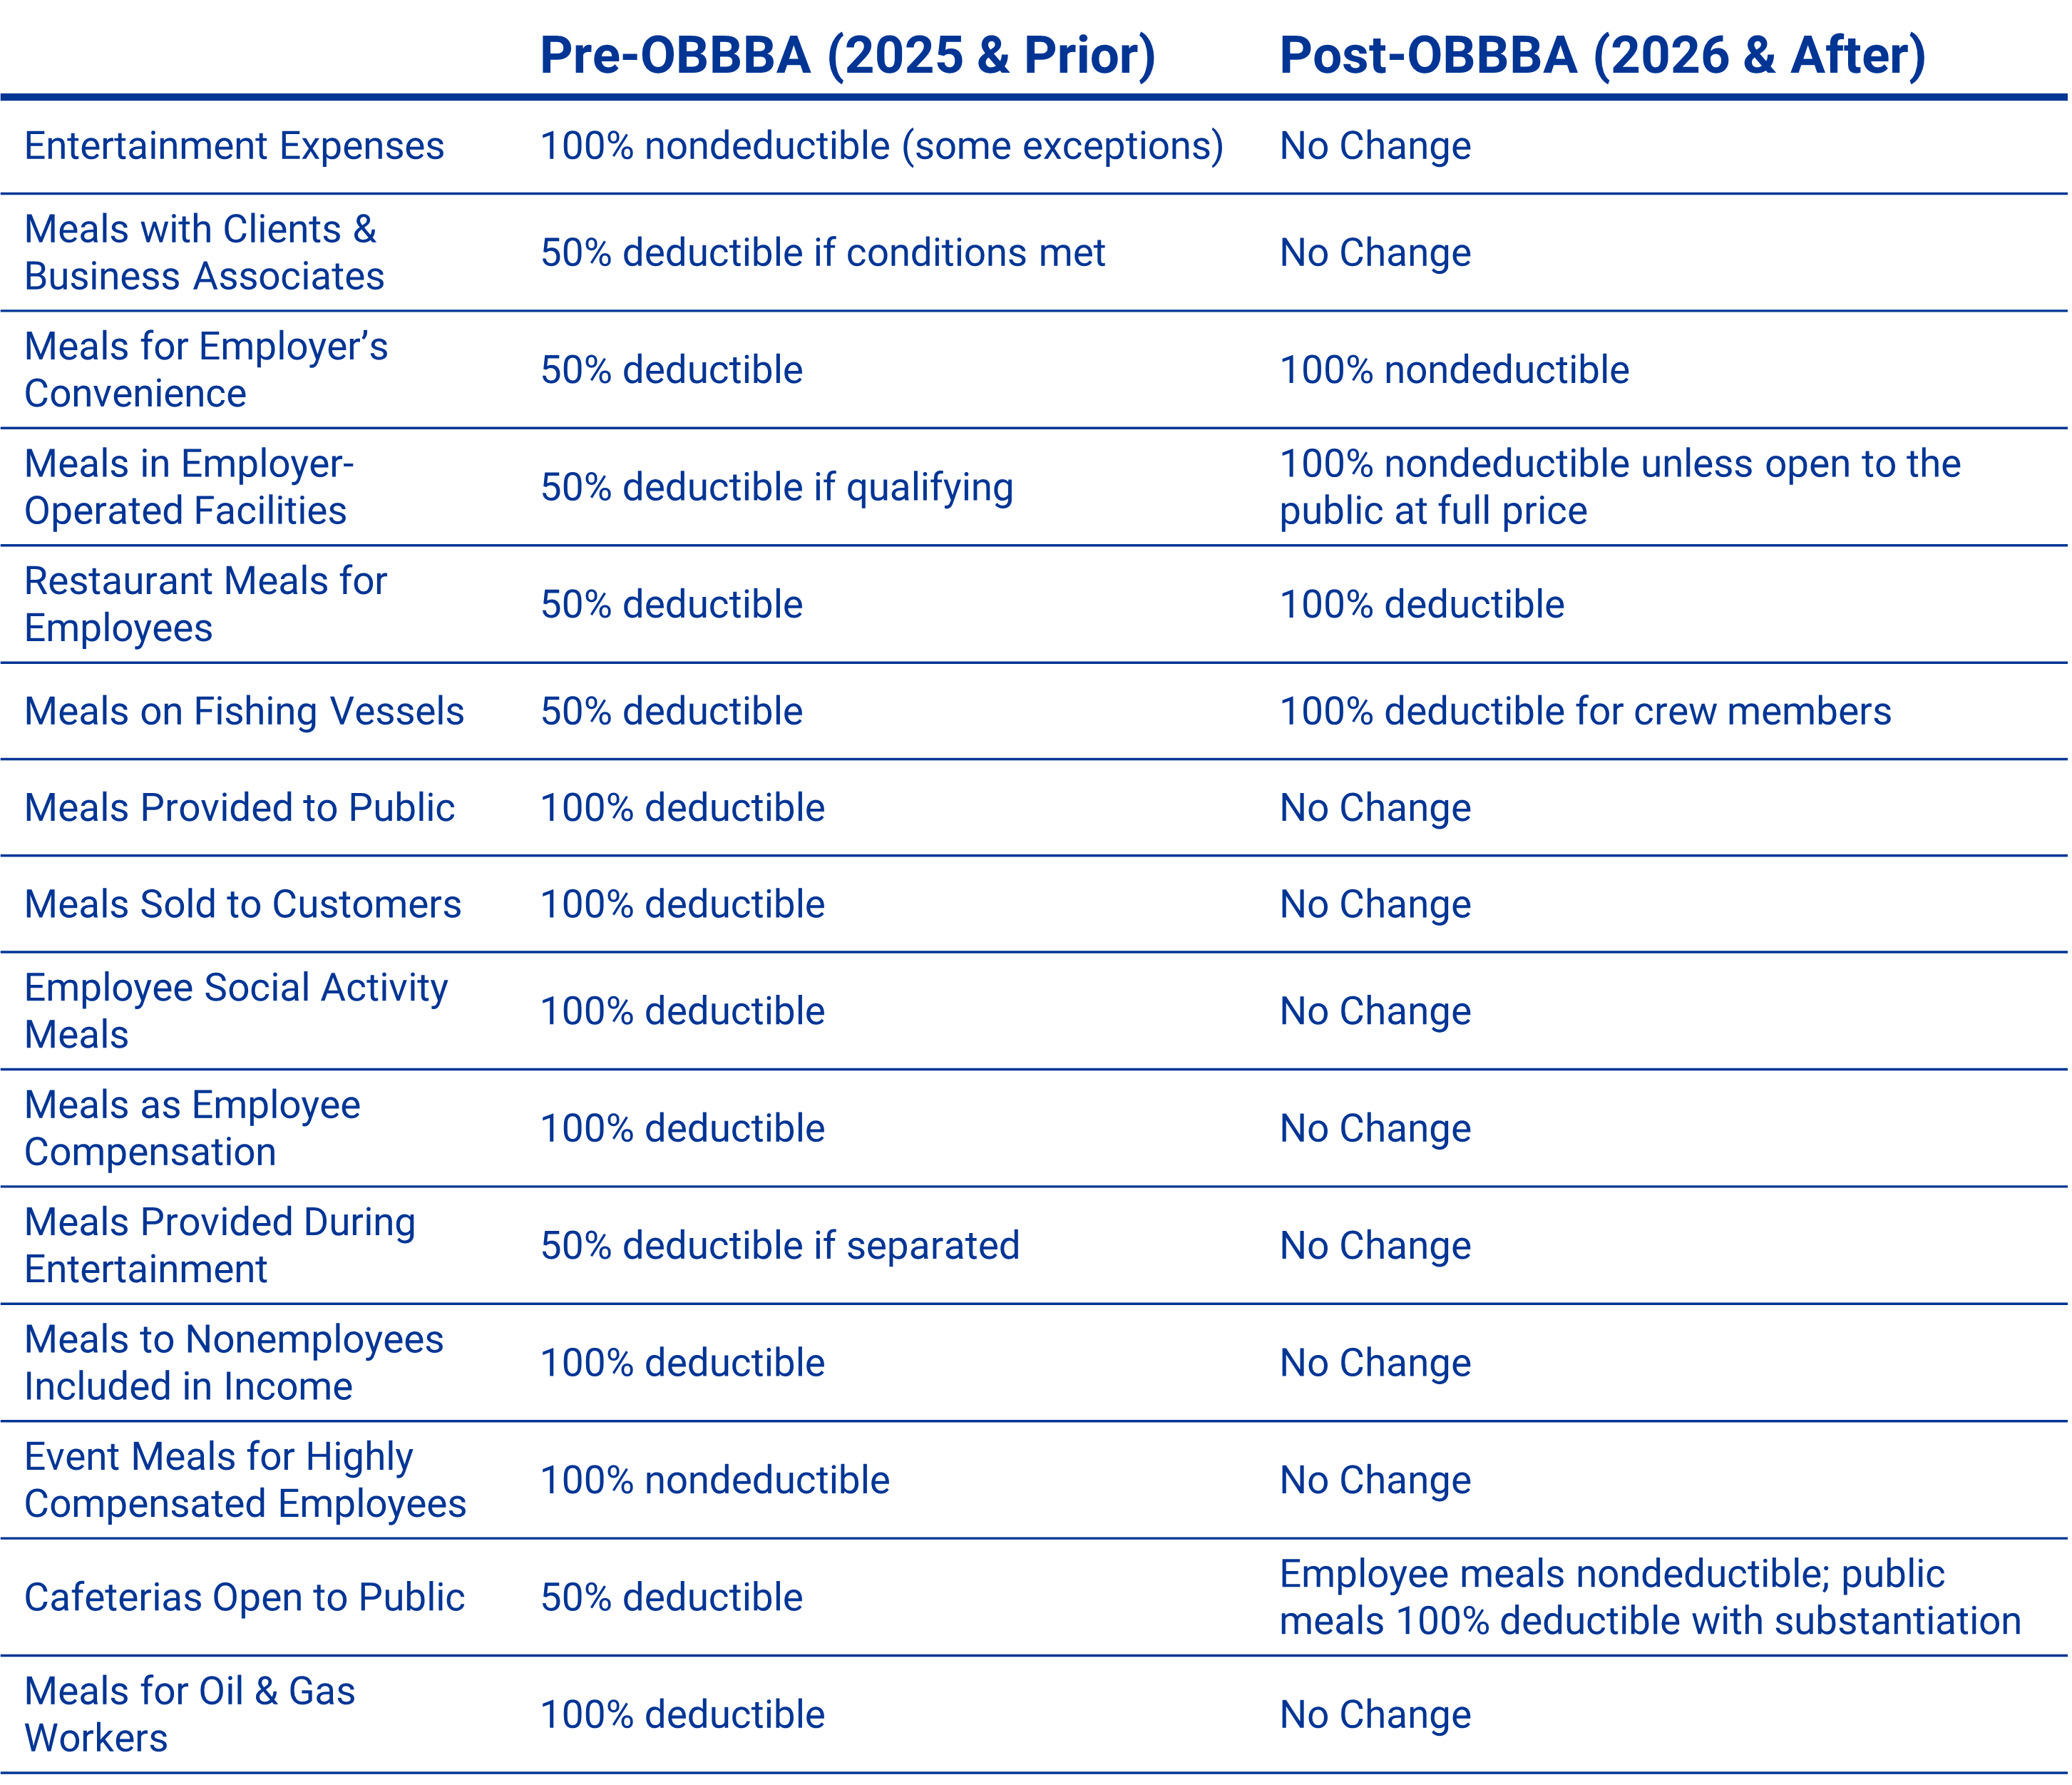
The One Big Beautiful Bill Act (OBBBA) brings new rules for meals and entertainment deductions beginning in tax years after December 31, 2025. While the categories haven’t changed much, the deductibility rules have. For business owners, this means far fewer employer provided meals will qualify. Only a limited set of specific situations will still allow a deduction under the new law.
At a Glance
Entertainment costs stay nondeductible (with only a few narrow exceptions).
Business meals remain 50% deductible, but you still need proper documentation and a clear business purpose.
Employer-provided meals become mostly nondeductible, including snacks, coffee, overtime meals, and meals served in on-site cafeterias. Exceptions include:
Meals provided by restaurants to their employees
Meals on fishing vessels
Meals sold to the public at full price in employer-operated cafeterias
Below is a table summarizing the changes:
Action Steps for Employers
Since the OBBBA significantly limits the deductibility of employer-provided meals, most businesses will need to make some operational and accounting adjustments. As you prepare for the 2026 tax year, consider the following:
Review how your company currently provides meals and snacks. Identify where food is being offered (e.g., break rooms, cafeterias, meetings, overtime support) and determine which items will no longer be deductible.
Update internal policies and communication. Employees may need clarity on what qualifies as a business meal going forward. Simple updates to handbooks, expense policies, or manager guidance can prevent confusion.
Adjust your accounting and tax processes. You may need new general ledger categories, revised tracking procedures, and updated tax provision and return calculations to reflect the new limitations.
Evaluate operational and financial impact. For companies with cafeterias or regular meal offerings, it may be worth assessing costs, pricing, and whether changes to operations make sense under the new rules.
We Can Help
The Elliott Davis team helps business owners adapt to the new tax requirements and the strategic decisions that follow. We can assist with policy updates, recordkeeping, and planning so you’re well prepared for the 2026 tax year. Contact us to discuss how these changes may affect your business and what steps to take next.
The information provided in this communication is of a general nature and should not be considered professional advice. You should not act upon the information provided without obtaining specific professional advice. The information above is subject to change.
U.S. regulators prioritize vendor management in 2025
Vendor management is a top regulatory focus in 2025, with examiners closely reviewing how banks assess, monitor, and manage third-party relationships.
March 25, 2025
Preparing for increased fair lending compliance scrutiny
Discover compliance risks, common pitfalls, and proactive strategies to help financial institutions strengthen fair lending practices and stay ahead of regulatory expectations.
March 13, 2025
Changes to the R&D Tax Credit Form 6765
Businesses that claim a research and development (R&D) tax credit must file Form 6765, Credit for Increasing Research Activities. The IRS has introduced significant changes to Form 6765 to take effect in the 2024 filing season.
March 11, 2025
Solving sales tax complexities for a growing real estate company
Real estate companies are particularly exposed to financial fraud due to their complex financial structures and decentralized banking operations. Implementing a financial automation platform to automate your accounts payable process helps safeguard financial transactions.
Case Study
March 10, 2025
What’s driving alternative investments in 2025?
Alternative investments are experiencing unprecedented momentum as investors seek higher returns, portfolio diversification, and protection against market volatility. Explore economic trends driving the demand for alternative assets.
March 6, 2025
Consequences of missing TINs on Form 1099-MISC
Employers should be aware of the consequences of filing Form 1099-MISC without recipient’s TIN.